
Many business owners use the same bank account for both personal and business transactions, thinking they will sort it out later. That habit is called commingling funds, and it is often the first step toward a bookkeeping nightmare. Commingling Funds: Why Mixing Personal and Business Finances is a Bookkeeping Nightmare is not an exaggeration—it is the reality our team sees when we step in to untangle mixed records.
When personal and business money flows through one account, you lose the ability to know whether your business is profitable, which expenses are legitimate, and what you owe in taxes. Worse, it can invite a Canada Revenue Agency (CRA) audit, trigger reassessments and penalties, and even strip away the limited liability protection your corporation was designed to provide. None of these outcomes are acceptable, yet they are all avoidable with clear financial separation.

What is Commingling of Funds in a Business Context?
Commingling occurs any time personal money and business money touch the same account or are used interchangeably. In a business context, it means paying business expenses from a personal credit card, depositing business revenue into a personal bank account, or using business funds for groceries, mortgage payments, or personal travel.
The Definition of Commingling
From a legal and accounting standpoint, commingling funds is the mixing of assets belonging to different owners or purposes. For a corporation, the money in the business account belongs to the corporation, not to you personally. When you treat corporate funds as personal funds, you blur the line between two separate legal entities. That blur makes accurate record-keeping nearly impossible and can have far-reaching consequences.
Why It Happens: Common Scenarios
Commingling rarely starts as a deliberate act. It typically begins with convenience: the business credit card is maxed out, so you use a personal card for a vendor payment; a customer pays you cash and you deposit it into your personal account because the business account is not handy; or you transfer money from the business account to cover a personal bill before year-end and intend to pay it back. Over time, these one-off exceptions become a pattern, and the paper trail disappears.
The Bookkeeping Chaos: Inability to Track Business Performance
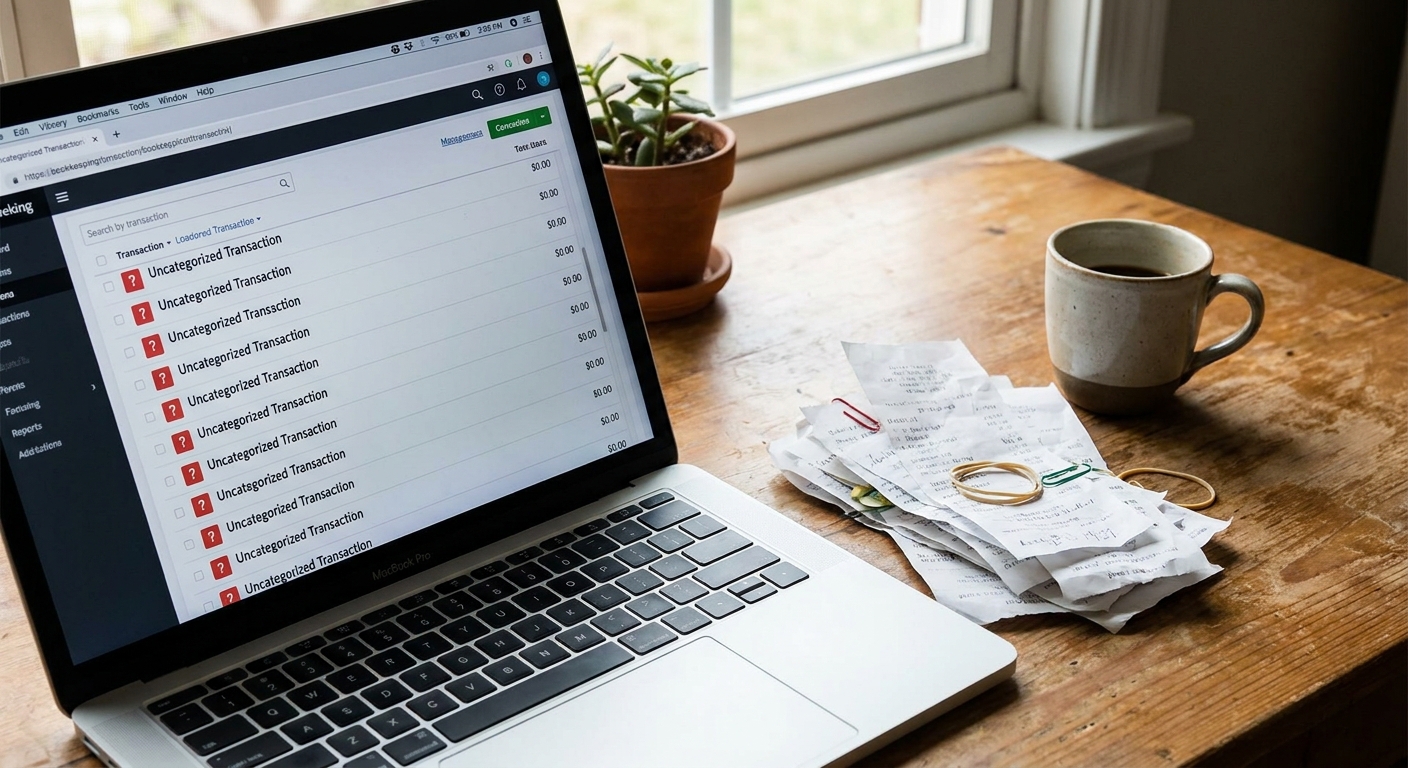
Your financial statements are only as good as the data that goes into them. When personal and business transactions share an account, every bank feed download becomes a puzzle. You cannot simply run a profit and loss report because the software cannot tell which transactions were for the business.
Mixing Transactions Makes Accurate Record-Keeping Impossible
Accurate bookkeeping requires categorizing every transaction by its business purpose. Commingling forces you or your bookkeeper to guess, cross-reference receipts, and ask questions for every fifth transaction. A single mixed account can triple the time required for monthly reconciliation, and even then the numbers may be wrong. Business owners who commingle often postpone bookkeeping for months because the task feels overwhelming, which compounds the problem.
Lost Deductions and Misreported Income
When personal expenses sit beside business expenses, legitimate business deductions get lost in the noise. You might forget to claim a deductible mileage expense or a home office cost because the transaction was buried among personal spending. At the same time, you may accidentally report personal income as business revenue or fail to capture cash receipts. Both errors distort your net income, leading to an incorrect tax return and an inaccurate picture of your company’s financial health.
CRA Red Flags and Audit Risk
The CRA expects to see clear separation between a taxpayer’s personal and business finances. When your bank accounts show a tangled mix, the agency cannot easily verify that the expenses you claimed were truly incurred to earn business income. That uncertainty is a red flag.
Why the CRA Scrutinizes Mixed Accounts
The CRA’s audit selection process looks for returns that contain inconsistencies or unsupported claims. A sole proprietor who reports a modest business income but has personal bank deposits far exceeding that amount will draw attention. For corporations, a shareholder loan account that is constantly in overdraft or personal expenses paid directly from the corporate account suggest the owner is using the corporation as a personal piggy bank. The CRA may then request bank statements and receipts, and if they cannot separate business from personal, they may treat all deposits as taxable income.
Common Triggers for an Audit
Several patterns commonly trigger CRA reviews when commingling is present: large, round-dollar transfers between personal and business accounts; a high volume of personal expenses claimed as business deductions (such as meals, travel, or vehicle costs); shareholder draws that are not documented as salaries or dividends; and frequent cash deposits into a personal account that are not reported as business revenue. If you are selected for a GST/HST audit, mixed accounts make it harder to prove input tax credits, and the entire return may be flagged for reassessment.
Penalties and Interest from CRA Reassessments
When the CRA disallows expenses because they cannot be substantiated as business costs, the consequences are not just a corrected return. The agency can reassess previous tax years, apply penalties, and charge interest from the original due date.
How the CRA Can Reassess Your Taxes
The CRA generally has the authority to reassess a tax return within three years for most taxpayers, and longer if they suspect misrepresentation due to neglect or fraud. If your mixed records lead the CRA to conclude you understated income or overstated deductions, they can reopen those years and issue a notice of reassessment. You then owe the additional tax, plus interest that has been accumulating since the original filing date.
The Financial Consequences of Disallowed Expenses
Disallowed business expenses increase your taxable income. For a corporation, that can mean additional corporate tax. If the expense was treated as a personal benefit to a shareholder, the CRA may include the amount in your personal income as a shareholder benefit, which is taxed at your marginal rate and may not be eligible for the dividend tax credit. On top of the tax, the CRA can apply a gross negligence penalty of up to 50% of the understated tax if they believe you knowingly claimed personal expenses as business costs. Even without negligence, a repeated failure to report income can trigger a federal and provincial penalty.
Loss of Limited Liability Protection (Piercing the Corporate Veil)
One of the main reasons to incorporate is to shield your personal assets from business liabilities. That shield exists only if you treat the corporation as a separate legal entity. Commingling funds is one of the fastest ways to lose that protection.
How Commingling Erodes Legal Separation
Courts and creditors look at whether you respected the corporate form. If you used the business bank account to pay personal grocery bills, transferred funds back and forth without documentation, or treated corporate property as your own, a judge may decide that the corporation is merely your alter ego. This is known as piercing the corporate veil. Once pierced, the corporation’s limited liability evaporates, and you can be held personally responsible for the business’s debts and legal judgments.
Personal Asset Exposure: A Real Risk
If your corporation is sued or goes bankrupt, commingling makes it difficult to prove which assets belong to the corporation and which belong to you personally. Creditors can argue that your personal bank account, home equity, or investments are actually corporate assets because you mixed them. In practice, we have seen how quickly a creditor’s lawyer seizes on a single personal expense paid from the business account to argue the entire corporate shield is invalid. That argument can put your family’s financial security at risk.
We have worked with business owners who faced exactly this situation after years of casual transfers between accounts. When we take on a case like that, we act as your dedicated representative with the CRA and creditors, working to document the corporate separation and protect what you have built.
Damage to Business Credibility and Financing Opportunities
Beyond taxes and legal liability, commingling sends a signal that your financial management is sloppy. Lenders, investors, and business partners all review your financial statements and bank activity before deciding to work with you. Mixed accounts make it impossible for them to trust your numbers.
Lenders and Investors See Risk in Poor Financial Hygiene
A bank considering a business loan will ask for bank statements and financial reports. If those statements show personal transactions mixed with business, the lender cannot assess your business’s ability to service debt. They may decline the loan or require personal guarantees, effectively negating the benefit of incorporation. Investors see commingling as a governance failure and a sign that the owner does not respect the business entity. That perception alone can kill a funding round.
Lost Partnerships and Growth Opportunities
Suppliers, landlords, and potential business partners often request financial references or a demonstration of financial stability. Commingled records make it hard to produce a clean set of books on short notice. You may miss out on a lease for a prime location, a vendor credit line, or a strategic partnership simply because you could not produce accurate financial statements. In our practice, we have helped clients clean up their books after a lost opportunity, but the best time to separate finances is before you need to prove your credibility.
Best Practices to Prevent Commingling
The good news is that commingling is entirely preventable. By setting up the right accounts and processes from the start, you can keep your business finances clean and your bookkeeping manageable.
Separate Bank Accounts and Credit Cards
The single most important step is to open a dedicated business bank account and a business credit card. All business revenue goes into the business account, and all business expenses are paid from the business account or card. Never use the business account for personal spending, and never use personal accounts for business purposes. If you are a sole proprietor, a separate business account is still essential—the CRA expects you to track business income and expenses separately, even if you report them on a personal tax return.
Use Accounting Software and Professional Bookkeeping
Accounting software linked to your business bank feeds makes categorization easier, but it is not a substitute for proper process. Many business owners start with software but still mix funds because they have not set up the right accounts. A professional bookkeeper can set up your chart of accounts, reconcile monthly, and flag any personal transactions that slip through. We recommend working with a bookkeeper who understands CRA requirements and can catch issues before they become a problem.
Establish Clear Reimbursement Processes
There will be times when you pay a business expense with personal money, such as buying supplies with a personal credit card in a pinch. That does not have to be a commingling disaster if you document it properly. Create a clear process: record the expense in an expense report immediately, note the business purpose, and reimburse yourself from the business account via a transfer or check with a clear memo. Do not let these reimbursements accumulate or become regular draws without documentation. If you are incorporated, pay yourself a salary or dividends through proper payroll or dividend resolutions, not ad hoc transfers.
Conclusion: Separate Your Finances to Safeguard Your Business
Commingling funds may feel like a small shortcut, but the consequences are anything but small. It creates a bookkeeping nightmare that obscures your true business performance, invites CRA scrutiny, leads to penalties and interest, strips away limited liability protection, and damages your credibility with lenders and partners.
Recap of the Consequences
To recap: mixed accounts make accurate record-keeping impossible; they raise red flags that can trigger a CRA audit; disallowed expenses lead to reassessments, penalties, and interest; personal asset exposure increases when the corporate veil is pierced; and your ability to secure financing or partnerships suffers. None of these are worth the convenience of using one account.
Take Action Today
The first step is to open a separate business account and business credit card if you have not already. Then, review the last three months of transactions and identify every personal expense paid from business funds or business expense paid from personal funds. Document those transactions, establish a reimbursement process, and commit to keeping the two worlds apart from now on. If the cleanup feels overwhelming, we can help you sort through the mixed records and set up systems that keep your business audit-ready and your personal assets protected. Schedule a confidential conversation with our team today.