
Most retailers treat inventory tracking and bookkeeping as two separate back-office tasks. But when those tasks are disconnected, the numbers stop telling the same story. Tracking inventory vs. bookkeeping is less about choosing one over the other and more about ensuring the systems behind them update in lockstep. For BC retailers, keeping these systems in sync is the difference between a clean month-end close and a frantic last-minute reconciliation.
The core issue is that inventory tracking is operational—what you have, where it is, what it cost—while bookkeeping is financial—how those inventory movements affect your profit and tax position. When a sale happens in your point-of-sale system but the journal entry for cost of goods sold isn’t created until later, your income statement and inventory valuation are temporarily wrong. That delay leads to inaccurate gross margin, misstated tax remittances, and decisions based on stale data.
Understanding Inventory Tracking and Bookkeeping
Before fixing the sync problem, it helps to separate the two functions. Inventory tracking answers questions about physical goods: how many units are on hand, what they cost, and where they are located. Bookkeeping answers questions about financial results: what revenue was earned, what expenses were incurred, and what profit remains. Both rely on the same underlying transactions, but they record them differently.
Defining Inventory Tracking
Inventory tracking is the operational process of recording the quantity and cost of items you buy, store, and sell. It includes purchase receipts, transfers between locations, sales, returns, and adjustments for damage or loss. In a modern system, each event updates an item’s on-hand count and often its average cost. The goal is to know exactly what you have available to sell at any moment, without physically counting everything.
Defining Bookkeeping
Bookkeeping is the systematic recording of financial transactions. For a retailer, that means entering sales revenue, cost of goods sold, freight, and inventory adjustments into the general ledger. Bookkeeping produces the income statement, balance sheet, and cash flow reports. Inventory appears on the balance sheet as a current asset, but only if the bookkeeping entries match the physical stock.
Key Differences and Overlaps
The overlap is the inventory asset account and the cost of goods sold expense. Every time you buy inventory, you are increasing an asset; every time you sell it, you are reducing that asset and recording an expense. Inventory tracking manages the physical and unit-cost side; bookkeeping manages the financial and tax side. A disconnect happens when the two sides use different timing, quantities, or costs for the same events.
- Inventory tracking updates stock counts and unit costs in real time.
- Bookkeeping records journal entries to reflect those changes in the general ledger.
- Overlap occurs at purchase and sale points, where both systems must agree.
Why Syncing Inventory and Bookkeeping Matters for Retailers
When inventory records and bookkeeping stay in sync, the financial statements you rely on are accurate without manual corrections. For a retail business, gross margin, inventory turnover, and tax remittances all depend on that accuracy. A mismatch can make a profitable business look like it is losing money, or hide a loss until it is too late.
Ensuring Accurate Financial Statements
Your income statement shows cost of goods sold as a direct offset to sales. If that cost is understated because inventory counts are off, your gross profit looks higher than it really is. Conversely, overstated costs depress profit and can lead to poor pricing decisions. The balance sheet is equally affected: an inventory asset that does not match the physical stock misrepresents the company’s working capital and equity.
Meeting Tax Compliance Requirements
Tax authorities require inventory to be valued consistently and reported accurately. In Canada, inventory must be valued at the lower of cost and net realizable value. If your bookkeeping records do not match your physical inventory, you may under-report or over-report taxable income. Sales taxes such as GST/HST and provincial sales tax must also be calculated on the correct selling price; a disconnect in inventory can lead to incorrect tax collected and remitted.
Improving Operational Efficiency
When systems are synced, you spend less time chasing discrepancies and more time serving customers. Month-end close becomes a review rather than a reconstruction. Purchase decisions can be based on live stock levels instead of guesswork. Staff can trust the system instead of double-checking every count. The result is faster reporting, fewer errors, and a clearer picture of which products actually make money.
- Reduce hours spent on manual reconciliation each month.
- Avoid overselling or stockouts that drive customers away.
- Make purchasing decisions from current, accurate data.
Common Challenges of Disconnected Systems
Many retailers run a point-of-sale system for sales and separate accounting software for bookkeeping, with inventory tracked in a spreadsheet. This setup forces someone to manually transfer data between systems. Each transfer is a chance for error, and the errors compound over time.
Data Silos and Manual Reconciliation
A data silo exists when sales data lives in the POS, inventory counts live in a spreadsheet, and financial records live in the accounting system. To close the month, someone exports sales, checks inventory, and enters journal entries by hand. That process takes hours and often contains typos, missed returns, or wrong cost assumptions. Even a small retailer can spend a full day each month just making the numbers line up.
Stock Count Discrepancies
Physical counts rarely match system counts perfectly. Theft, damage, returns, and data entry mistakes all create differences. When inventory tracking and bookkeeping are disconnected, those differences are hard to isolate. You might adjust the inventory count but forget to record the corresponding bookkeeping entry, or record a bookkeeping entry that does not actually fix the physical discrepancy. Over time, the two systems drift apart until neither is trustworthy.
Delayed Financial Insights
If bookkeeping is updated only at month-end, the financial reports you see during the month are stale. You might think you have healthy margins on a product line, but by the time the books catch up, the pricing decision has already hurt you. Real-time or near-real-time sync means you can see margin trends as they happen, not after the damage is done.
Inventory Accounting Essentials: Cost Methods and COGS
Accurate sync requires consistent inventory costing. The cost you assign to each unit sold becomes your cost of goods sold (COGS). Choosing a costing method and applying it uniformly is the foundation of reliable bookkeeping.
FIFO, LIFO, and Weighted Average
The three most common methods are first-in, first-out (FIFO); last-in, first-out (LIFO); and weighted average cost. FIFO assumes the oldest inventory is sold first, which often matches the physical flow of goods and leaves recent costs in ending inventory. Weighted average recalculates an average cost for all units after every purchase. LIFO assumes the newest inventory is sold first and is not accepted for tax purposes in Canada, though it may be used for internal analysis. For Canadian retailers, the CRA generally accepts FIFO, weighted average, and specific identification.
- FIFO: best for perishable goods or items with stable or rising costs.
- Weighted average: smooths cost fluctuations and simplifies bookkeeping.
- Specific identification: used for high-value unique items such as vehicles or artwork.
Calculating Cost of Goods Sold (COGS)
COGS is calculated as: beginning inventory + purchases – ending inventory = cost of goods sold. Each element must come from the same system and use the same costing method. If your ending inventory count is wrong, your COGS is wrong, and so is your gross profit. For example, if ending inventory is overstated by $5,000, COGS is understated by $5,000, and net income is overstated by $5,000 before tax. That single error can create a material misstatement.
Impact on Financial Reporting
Your choice of costing method affects both the balance sheet and the income statement. In a period of rising prices, FIFO produces a higher ending inventory value and lower COGS, resulting in higher reported profit. Weighted average lies between FIFO and LIFO. Consistency is required: once you choose a method, you should apply it consistently from year to year unless you get approval to change. Changing methods without adjusting prior periods can distort comparability and attract audit attention.
Tax Compliance for Retail Inventory
Retail inventory carries specific tax obligations. The rules are designed to ensure you report the correct taxable income and remit the correct sales taxes. Failure to keep inventory and bookkeeping in sync can lead to underpaid taxes, interest, and penalties.
Inventory Valuation Rules
For tax purposes, inventory must be valued at the lower of cost and net realizable value. Cost includes the purchase price plus any costs to bring the goods to a saleable condition, such as freight and import duties. Net realizable value is the estimated selling price less any costs to complete and sell. If your bookkeeping records use an inflated cost, you may be understating income; if you use a deflated cost, you may be overstating income. Year-end physical counts are essential to verify the actual value.
Handling GST/HST and PST
When you sell inventory, you collect GST/HST on the sale price. When you buy inventory, you pay GST/HST and can usually claim an input tax credit. Some provinces also have a separate provincial sales tax that applies to retail sales but not to purchases for resale. Your accounting system must track these taxes correctly at each transaction, and your inventory records must support the tax collected and remitted. A disconnect between sales records and inventory can lead to either under-remitting or over-remitting sales tax, both of which create audit exposure.
Reporting Obligations to Avoid Audit Risks
Tax authorities cross-reference sales reported on GST/HST returns with income reported on corporate tax returns. Large unexplained differences in inventory or cost of goods sold are a common red flag. To reduce audit risk, keep detailed records that tie each inventory movement to a bookkeeping entry: purchase invoices, sales receipts, shipping documents, and inventory adjustment logs. If a physical count reveals a shortage, record the adjustment in both inventory and bookkeeping at the same time.
- Retain purchase and sales invoices with tax amounts clearly shown.
- Document any inventory write-downs or write-offs with supporting evidence.
- Reconcile inventory records to the general ledger at least monthly.
Best Practices for Accurate Inventory Tracking
Accurate inventory tracking is not a one-time project; it is a set of habits. The most reliable retailers we work with treat inventory accuracy as part of the bookkeeping cycle, not an afterthought. We have spent decades helping retail businesses reconcile their stock and ledgers, and the practices below come directly from that work. Insurance professionals stress the same discipline for physical goods: the managing directors at Insureline Alder, drawing on over 25 years of combined experience, advise in their guidance on documenting inventory for potential claims that records should be a living document—updated continuously, backed up securely offsite, and detailed with accurate valuations.
Conducting Regular Inventory Audits
Full physical counts once a year are not enough for synced systems. Cycle counting—counting a small portion of inventory on a rotating schedule—keeps the system honest without shutting down the store. High-value or fast-moving items should be counted more frequently. Any discrepancy should be investigated immediately: check for unposted sales, purchase receipts not entered, theft, or data entry errors. Record the adjustment in both inventory and bookkeeping on the same day.
Monitoring Key Performance Indicators
Track metrics that reveal whether your inventory and bookkeeping are in harmony. Inventory turnover ratio (COGS divided by average inventory) shows how quickly stock is selling. Days sales of inventory (DSI) indicates how many days it takes to sell the entire inventory. Gross margin return on investment (GMROI) measures how much gross profit you earn for each dollar invested in inventory. If these metrics change unexpectedly, it usually means a sync problem.
- Inventory turnover: too low means overstocking; too high may mean stockouts.
- Days sales of inventory: compare to your industry average to spot inefficiency.
- Gross margin return on investment: prioritizes products that earn the most profit per dollar tied up.
Forecasting Demand to Prevent Stockouts
Use sales history, seasonality, and current trends to predict future demand. When inventory tracking is synced with bookkeeping, you can run reports that show which products are selling and how much profit each generates. Forecast future sales by month and set reorder points that trigger purchase orders before stock runs out. Avoid both stockouts, which lose sales, and overstocks, which tie up cash.
Automating Data Flow Between Inventory and Accounting Systems
The most effective way to keep inventory and bookkeeping in sync is to automate the data flow between them. Instead of exporting and importing spreadsheets, set up integrations so that every sale, purchase, return, and adjustment updates both systems automatically.
Integrating POS and E-commerce Platforms
Your point-of-sale system and e-commerce platform are where inventory moves. Connect them to your accounting software through built-in integrations or middleware. When a customer buys an item, the sale is recorded in both systems: inventory decreases by one unit, revenue increases, and cost of goods sold is posted. When you receive a purchase order, inventory increases and accounts payable is recorded. Returns reverse these entries automatically, reducing human error.
Real-Time Inventory Updates and Financial Entries
With a real-time integration, there is no lag between a physical event and its financial record. This allows you to see current gross margin by product, monitor stock levels across locations, and know your cash position at any moment. Real-time sync is especially valuable during busy sales periods, when waiting for month-end manual entries can hide a cash flow problem until it is too late.
Reducing Manual Data Entry Errors
Every manual entry is a chance to transpose a number, misclassify a transaction, or omit an adjustment. Automation reduces the number of manual entries to exceptions only. For example, the integration handles routine sales and purchases, while you manually record only unusual events such as damaged goods or adjustments. This shifts your team’s time from data entry to exception review and decision-making.
Selecting Software for Seamless Integration
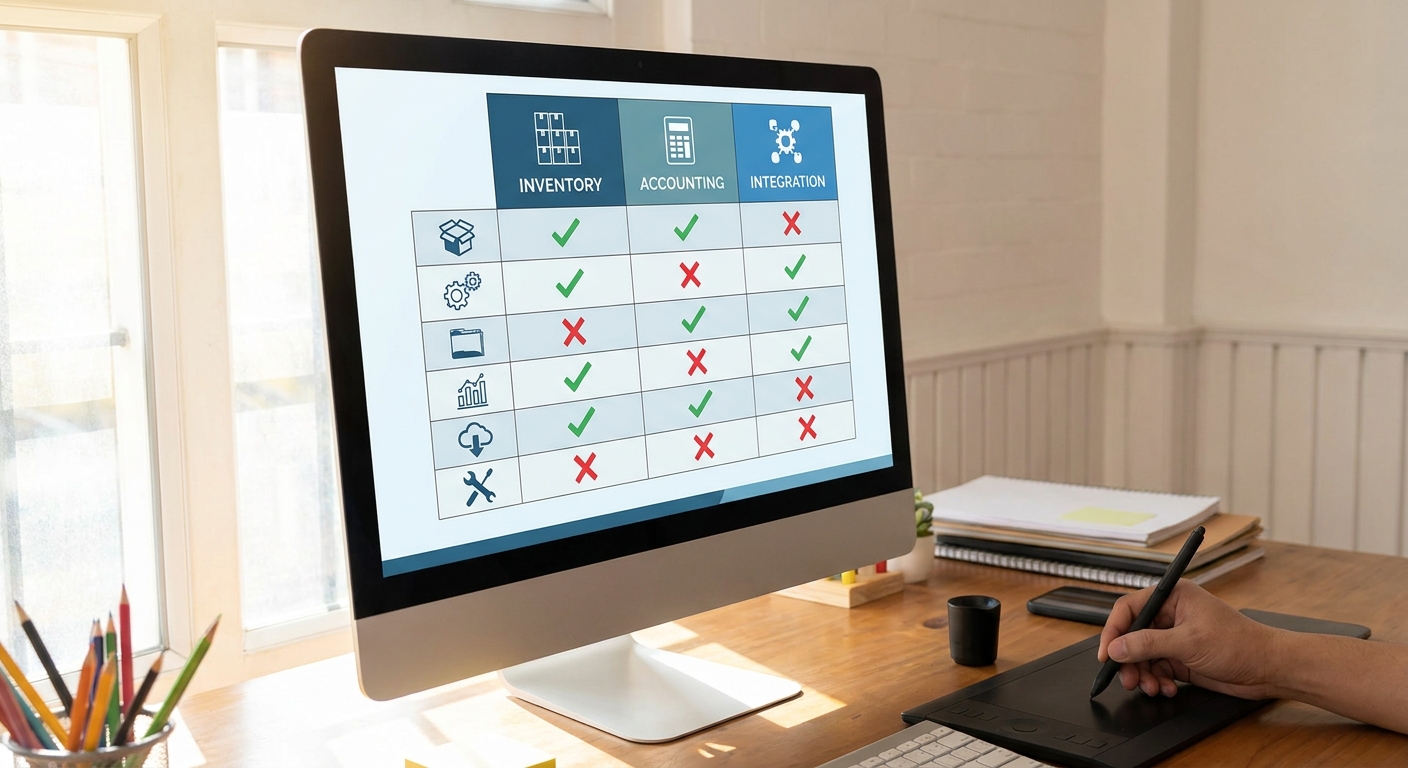
Not all retail software connects well with accounting systems. When evaluating options, look for platforms that treat inventory and bookkeeping as one workflow rather than two separate modules with a weak link.
Essential Features to Look For
- Real-time stock tracking: automatically updates on-hand quantities after every sale or receipt.
- Cost method support: at least weighted average and FIFO, with the ability to use specific identification.
- GST/HST and PST handling: automatically calculates tax based on customer location and item tax status.
- Purchase order management: tracks incoming stock and matches invoices to receipts.
- Multi-location inventory: if you have more than one store or warehouse, the system must track stock separately.
- Sales and margin reports: shows gross profit by product, category, or location.
- POS and e-commerce integration: connects to your existing sales channels without custom coding.
Canadian Tax Compliance Support
Software designed for the Canadian market will have tax rates built in for GST/HST and provincial sales tax where applicable. It should let you set different tax rules for different products and customer locations. The system should also produce reports that help you complete your sales tax returns and reconcile tax collected on sales with tax paid on purchases. Avoid systems that require manual tax calculations or third-party tax add-ons, as they reintroduce the exact manual effort you are trying to eliminate.
Scalability for Growing Retailers
Choose a system that can grow with you. If you plan to add a second location, an online store, or a new product line, the software should handle that without a rebuild. Look for a platform that allows additional users, more SKUs, and higher transaction volumes without degrading performance. Scalability also means the integration should remain reliable as your sales volume increases, so you do not outgrow the sync pipeline.
Manual vs Automated Sync: Efficiency Comparison
Retailers often ask whether they can get by with manual sync until they grow. The answer depends on transaction volume, but almost every retailer reaches a point where manual sync costs more in time and errors than the effort to automate.
Time Savings and Accuracy
A manual sync process might take several hours each month just to export, cross-check, and enter journal entries. With automation, that monthly routine drops to perhaps an hour of exception review. Accuracy improves because the system applies consistent costing and tax rules to every transaction. A missed return or duplicate invoice becomes a rare exception that the system flags, rather than a hidden error that surfaces at year-end.
Scalability and Flexibility
Manual sync breaks down as SKU counts and transaction volumes grow. A spreadsheet with 200 products is manageable; 2,000 products is not. Automated sync scales with your business because the system processes each transaction the same way, whether you have 10 sales a day or 1,000. It also gives you flexibility: you can add new sales channels or locations without redesigning the entire bookkeeping workflow. The efficiency gains compound, freeing up time to focus on merchandising, customer service, and strategy.
Conclusion: Keeping Your Systems in Sync
Tracking inventory vs. bookkeeping is not a choice between two functions; it is a design problem that every retail business must solve. When the systems are disconnected, financial statements become unreliable, tax compliance becomes risky, and operational decisions suffer. By understanding the differences, choosing consistent costing methods, maintaining tax records, and automating the data flow, you can keep both sides of your retail operation telling the same story.
If your inventory and bookkeeping are still out of sync, we can help you map the integration and reduce manual reconciliation. Contact our office to discuss your retail accounting setup.